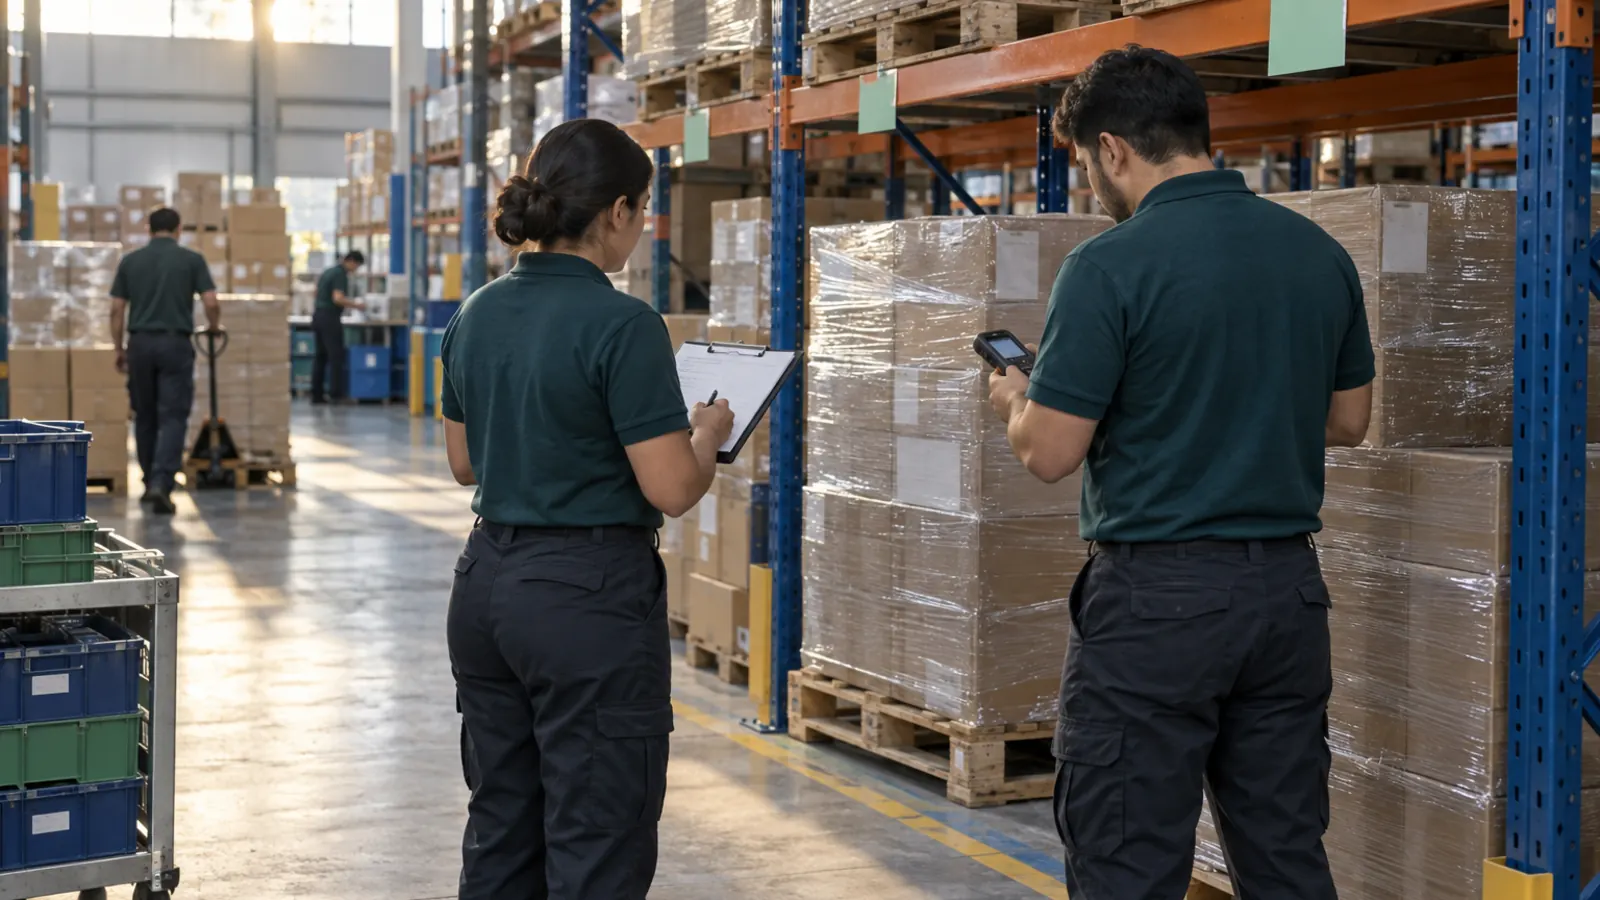
December puts two pressures on a warehouse in Mexico at once: peak season volume and the fiscal year-end, since Mexico's fiscal year is the calendar year. When the year-end count is prepared in the last week of December, the results are rushed counts, open documents, third-party goods counted as the company's own and January adjustments without documented support.
This article covers what the warehouse must resolve before December 31. For US companies with Mexican subsidiaries, the same count usually serves both the Mexican statutory requirements and the parent company's year-end.
What the law requires and what your accountant decides
Mexico's income tax law (Ley del Impuesto sobre la Renta) requires companies under the general regime to take a physical inventory as of the end of the fiscal year (article 76, section IV) and to keep inventory control under a perpetual inventory system (article 76, section XIV). Article 41 of the same law lists the valuation methods a taxpayer may choose: first in, first out, specific identification, average cost and the retail method. The Federal Tax Code (Código Fiscal de la Federación), article 28, includes inventory control and the valuation method among the records that make up a company's accounting.
Responsibilities should be defined from the outset: the valuation method, the date used for the close and the tax treatment of each discrepancy are decided by your accountant. The warehouse is accountable for reliable quantities by product, lot and location, and for the evidence of how they were obtained.
November: agree on the date and the method
The first meeting between the warehouse and accounting should answer four questions:
- When do we count? On the closing date or a nearby one, reconciling movements recorded between the two dates, if your accountant accepts it. Counting on December 31 competes with operations; counting in the first days of January with the warehouse closed is a common alternative.
- Do we count everything or by zone? A warehouse with a reliable cycle counting program may be able to reduce the scope of the year-end count; that decision belongs to your accountant and, if you have one, your auditor.
- Who observes? If the company has an external audit, the auditor usually attends the count and takes test counts. Their audit plan should be known in advance.
- What evidence is delivered? Detail by location, discrepancies, recounts and adjustments with their approval.
The document cutoff
The inventory cutoff is the point after which all receipts and issues in the area to be counted are suspended; it determines which documents belong to the fiscal year. Cutoff errors are among the most costly because they affect inventory and payables or receivables at the same time:
- Goods received without a closed document: they are physically in the warehouse but not recorded in the system. They show up as an overage.
- Goods shipped without the issue recorded: they are recorded in the system but no longer in the warehouse. They show up as a shortage.
- Invoices and shipments on different dates: a sale invoiced on the 31st that ships on January 2, or the reverse. The warehouse should tell accounting which shipments left before and after the cutoff.
Close every pending receipt, transfer and return before the cutoff date, and record the exact time of the last document of each type.
Third-party goods and goods outside the warehouse
Before the count, list the goods that require different treatment:
- Supplier consignment stock that sits in your warehouse but is not yours until used or sold.
- Customer goods held in storage or for repair.
- Goods in transit, between warehouses or on the way from a supplier, which cannot be physically counted.
- Goods held by third parties: at a contract manufacturer, an outside warehouse or on display at a customer.
What is physically in the warehouse but does not belong to the company is separated and identified so it is not counted as owned. What belongs to the company but is elsewhere is documented with the third party's confirmation.
Damaged, expired or obsolete product
At year-end, the company recognizes goods that will not sell at their recorded value. Identify them before the count, move them to a quarantine or damaged-goods location and give the list to accounting. In Mexico, destroying goods for a tax deduction requires advance notice to the tax authority, so the process must start early. Whether to destroy, donate or sell at a discount, and the related tax requirements, are decided by your accountant.
In Chainlink WMS, every stock record has a status (available, quarantine, in transit, staged for shipping, damaged or blocked) and only available stock is allocated to picks. In the Professional and Enterprise plans, the inventory aging dashboard in advanced analytics shows units by age range and expiration range, and it exports to Excel.
The file for your accountant and auditor
When the count is done, the warehouse delivers:
- Count detail by location, product, lot and quantity.
- The discrepancies found and the recount for each.
- The adjustments posted, with their reason and who approved them.
- The list of third-party goods, goods in transit and goods held by others.
- The list of damaged, expired or obsolete product.
- The cutoff time and the last document of each type.
With a WMS, much of this file comes out of the system. In Chainlink, the stock ledger lists every movement with its date, user, document, origin and destination; when a count is closed, results are split into matches, wrong location, overages, shortages and items not in the system, and adjustments are posted by a user with an Administrative license. The web platform is available in English for controllers who review the file from abroad.
Frequently asked questions
Is a physical inventory required at fiscal year-end in Mexico?
Mexico's income tax law requires companies under the general regime to take a physical inventory as of the end of the fiscal year (article 76, section IV). How to comply, including the scope of the count, should be defined by your accountant.
What is the document cutoff in an inventory count?
It is the point after which all receipts and issues in the area to be counted are suspended; it determines which receipts and shipments belong to the period. A deficient cutoff causes goods to be counted twice or not at all.
How is consignment stock handled in the count?
Supplier consignment stock sits in your warehouse but does not belong to your company. It is separated, identified and not counted as owned; how it is recorded is defined by your accountant.
Share this article: LinkedIn