In many warehouses, damaged, expired or obsolete goods accumulate during the year without a defined disposition. When a write-off is requested in December, the deadlines, notices and evidence requirements that apply in Mexico no longer fit in the last two weeks of the fiscal year. A company in Mexico that wants the tax deduction must notify the tax authority (SAT) before destroying the goods, a step that teams used to internal write-off paperwork often overlook. The tax treatment is not the warehouse's decision, but the warehouse holds the information that supports it.
This article covers what to prepare from the warehouse. It is not tax advice: the procedure, notices and accounting entries are defined by your Mexican accountant. Mexico's fiscal year is the calendar year, so year-end is December 31.
What the law says
Mexico's income tax law (Ley del Impuesto sobre la Renta), article 27, section XX, allows deducting from inventory the value of goods, raw materials and semi-finished or finished products that lost their value through deterioration or other causes not attributable to the taxpayer, in the year it happens and subject to the regulations. The same section requires that basic necessities for human subsistence (food, clothing, housing or health) be offered for donation to authorized institutions before destruction, unless another law prohibits their sale, supply or use.
The income tax regulations set the deadlines:
- Article 107. The destruction must be notified to the SAT at least thirty days before the planned date, with the data on the goods, the destruction method, date, time and place, and it is recorded in the accounts of the year in which it takes place.
- Article 108. For basic necessities, the donation offer is notified online to the SAT at least fifteen days before the first destruction. If the goods have an expiration date, the notice must be filed no later than five days before expiration; for medicines, no later than six months before.
With a thirty-day notice, a destruction scheduled before December 31 requires filing the notice by late November.
What the warehouse provides
1. Identify
Walk the warehouse with accounting and quality, and prepare a list of the goods that lost their value: damaged product, expired product, product close to expiration with no chance of sale, items made obsolete by a model or packaging change, returns that cannot be resold. For each line: product, lot, expiration date, quantity, location and cause.
2. Segregate
Move those goods to a marked quarantine zone and block it so nothing is allocated to an order. Goods that are not segregated are picked by mistake or leave inventory without a record.
3. Document
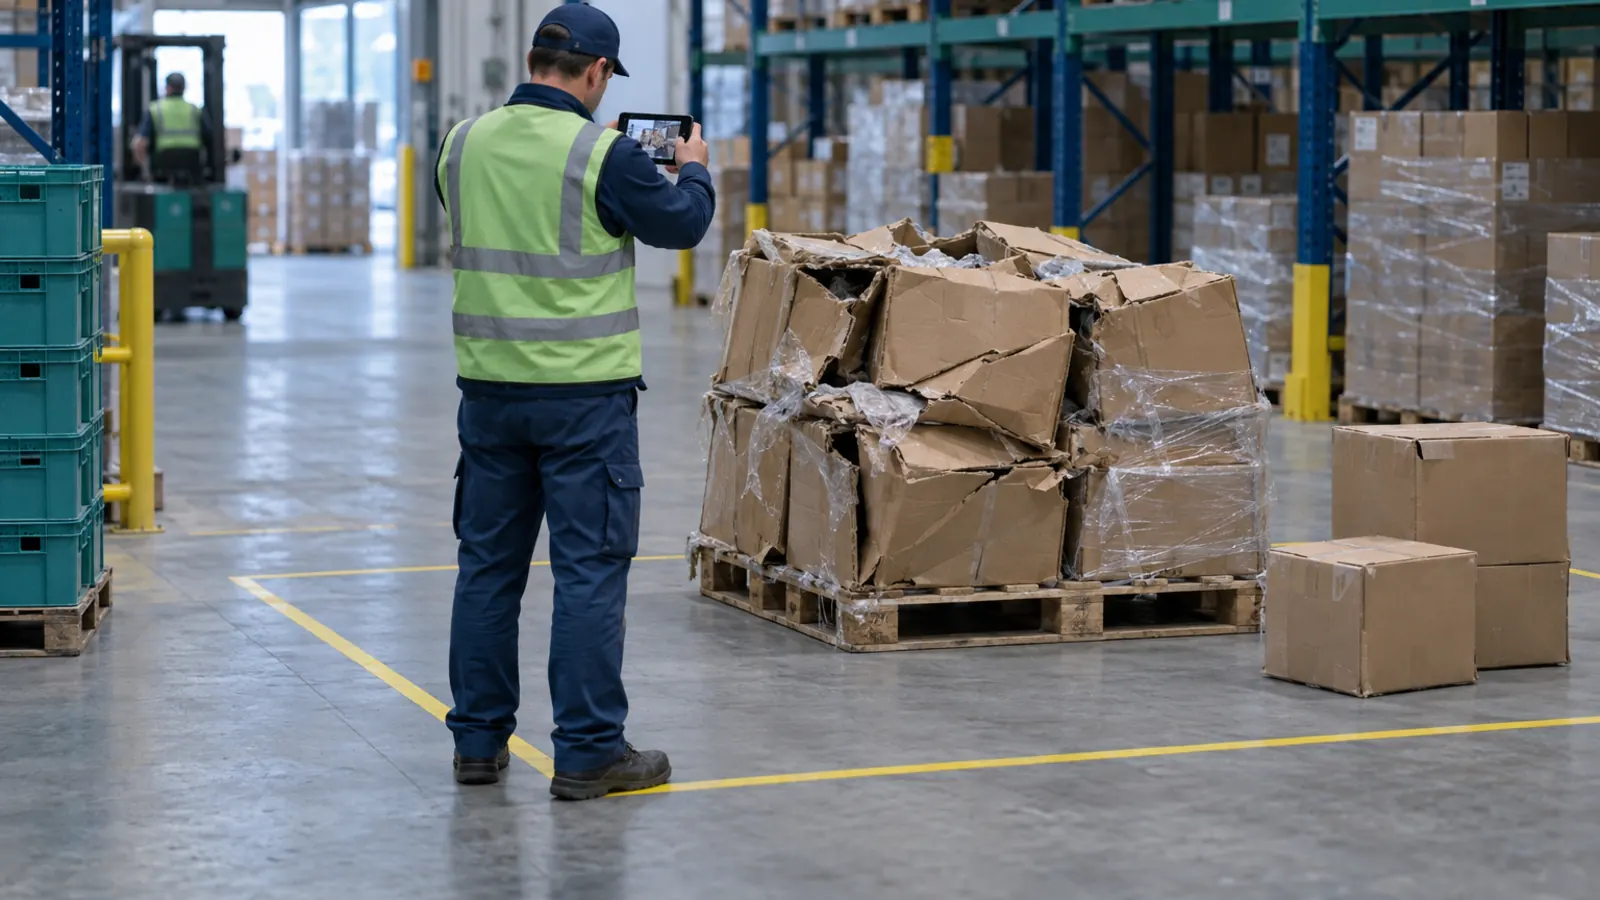
Photograph each line, with its lot label visible when there is one. Keep the documents that explain the cause: the carrier's damage report, the claim to the supplier, the return inspection, the quality report. The auditor or the SAT may ask you to show that the loss of value was not attributable to the company.
4. Keep the goods until final disposition
Between the notice and the destruction or donation, the goods must remain in the warehouse and match the notified list. If part of it is sold, moved or destroyed early, the list no longer matches.
5. Record the issue
When the goods are destroyed or donated, record them as an issue with a reason. The quantity recorded in quarantine and the quantity destroyed must match.
Suggested calendar
| Approximate date | Task | Owner |
|---|---|---|
| First half of November | Walk-through, list by product and lot, move to quarantine | Warehouse, quality |
| Second half of November | Review of the list and tax method; donation offer for basic necessities | Accounting |
| Before the end of November | Destruction notice at least 30 days in advance | Accounting |
| December | Destruction or donation with evidence | Warehouse, accounting, destruction provider |
| At close | Record issues and reconcile with the notified list | Warehouse, accounting |
Adjust the calendar to your close and to what your accountant defines. If your year-end physical count happens at the same time, coordinate this work with the steps in the article on the year-end count in Mexico: goods to be destroyed are counted and segregated before the general count.
How to prevent accumulation next year
- Review inventory aging every month, by age and by expiration range.
- Apply FEFO (first expired, first out) to products with expiration dates so the lot that expires first ships first.
- Require a minimum remaining shelf life at receiving, so you do not accept lots that will expire before they sell.
- Disposition returns in days, not months.
How Chainlink records it
In Chainlink WMS, stock has a status: available, quarantine, in transit, staged for shipping, damaged or blocked, and only available stock is allocated to picks. A location can be blocked with a reason. In returns, inspection assigns each unit a disposition (restock, quarantine, scrap or return to supplier) with a reason that can require a photo; scrap leaves inventory with its reason in the stock ledger and requires a supervisor's permission. With lot and expiration control, receiving stops when a lot expires before the minimum shelf life and picking allocates the lot that expires first. In the Professional and Enterprise plans, analytics show inventory aging by age and expiration range. Chainlink does not file notices with the SAT or keep the accounting.
Frequently asked questions
Can destroyed inventory be deducted in Mexico?
The income tax law allows deducting goods that lost their value through deterioration or other causes not attributable to the taxpayer, subject to its regulations, including the destruction notice. Your accountant decides whether it applies and how to document it.
How far in advance must the destruction be notified?
The income tax regulations require at least 30 days before the planned date. For basic necessities offered for donation, the donation notice is due at least 15 days before the first destruction, with special rules for products with expiration dates.
What evidence should the warehouse keep?
The list by product, lot and quantity, the quarantine location, photos, the documents explaining the damage or expiration, and the record of the issue when the goods are destroyed or donated.
Share this article: LinkedIn