Every company has fixed assets: computers, furniture, tools, vehicles, machinery. In every case, control requires knowing where each one is, in what condition, who it is assigned to and whether it matches the accounting record. This article describes what RFID solves in that control and how to implement it.
Current practice and its limitations
In many Mexican companies, asset control follows a pattern: once a year, a team walks offices, plants and branches with a printed list, checks that each asset exists, that its serial number matches and that it is where the record says. The results are consistent:
- The walk-through takes days. With thousands of assets across several sites, the count takes several business days from several people.
- The record loses accuracy quickly. Assets that moved offices without notice, retired equipment still on the books, computers assigned to people who no longer work there.
- Accounting reconciliation is hard. Mexico's income tax law (Ley del Impuesto sobre la Renta) allows investments to be deducted by applying an annual percentage to their original amount (article 31), so the record must identify each asset with its amount and date. A record that does not match what exists makes that deduction harder to support. The tax treatment of each case belongs to your accountant.
What an RFID fixed asset system is
It is a system that identifies each asset with a radio frequency (RFID) tag and links it to its record: asset number, description, location, custodian and accounting data. Unlike a barcode, which must be seen and read one at a time, a UHF RFID reader reads many tags at once and at a distance, without line of sight.
Components
- Passive UHF tags. No battery: they respond with the energy the reader emits. There are models for each surface: adhesive labels for plastic, wood or cardboard; on-metal tags for equipment and machinery; and encapsulated tags for moisture, dust or chemicals.
- Handheld readers. A handheld with a built-in RFID reader or a reader that attaches to the handheld, for counts and searches.
- Fixed readers with antennas. Installed at entrances or checkpoints to record when an asset enters or leaves an area.
- Software. Receives reads, compares them with the asset register and shows what is missing, what is extra and what moved.
What it solves
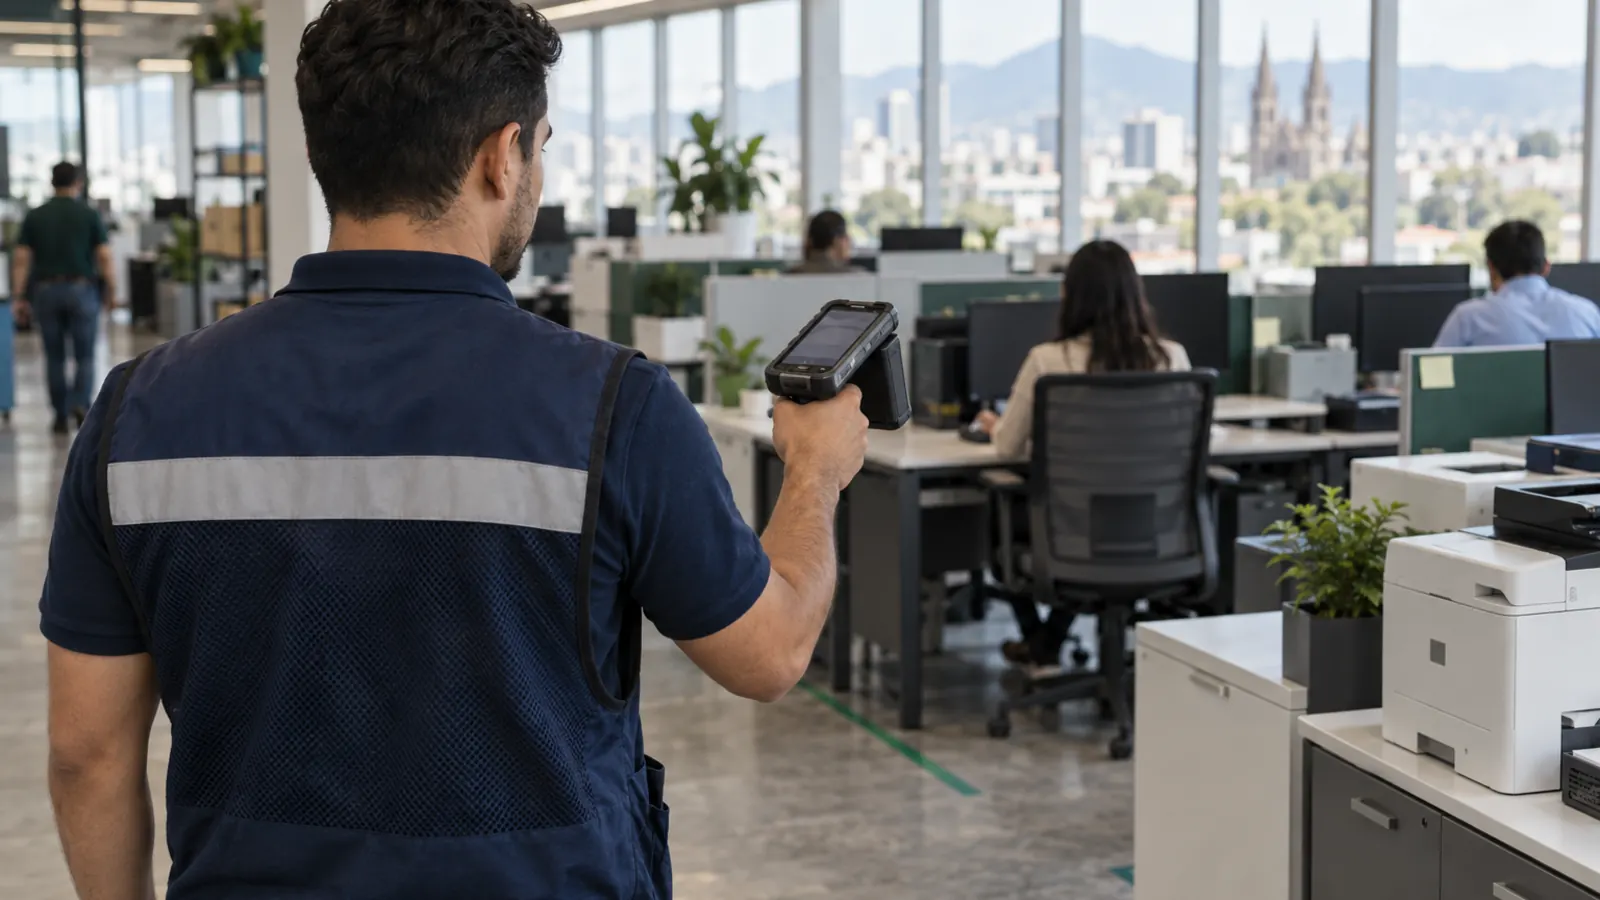
Faster counts. The reader records every tag in range while the person walks the area, instead of scanning one code per asset. A count that took days can be reduced to hours; the exact reduction depends on how dispersed the assets are and is measured in a pilot.
One identifier per asset. Each tag carries a unique code, the EPC, linked to a single asset. A tag read several times counts as one asset.
Entry and exit records. With fixed readers at entrances, each time an asset passes a checkpoint it is recorded with date and time, for example when lab equipment is lent between departments.
Proximity search. Many handheld readers have a locate mode that shows a tag's signal strength and guides the person toward it.
Which assets can be tracked
Almost any physical asset can be tagged. The most common:
- Offices: computers, monitors, printers, projectors, furniture and telecom equipment.
- Plants: machinery, tools, molds, returnable containers and safety equipment.
- Education and research: lab and audiovisual equipment.
- Public sector: vehicles, IT and communications equipment, and furniture.
How to implement it, step by step
1. Diagnosis and scope
Before buying equipment, answer:
- How many assets does the company have, and in how many locations?
- Which surfaces will the tags go on: metal, plastic, wood?
- Do you only need counts, or also entry and exit records with fixed readers?
- How will the asset register connect to your accounting system?
2. Tag testing
This step has the most influence on the result. A tag that reads well on plastic may not read on metal. Test several models on the real assets, in their real location, before buying in volume. A test with 50 to 100 assets of different types is usually enough to choose.
3. Tagging and registration
This is the most labor-intensive stage: each tag is linked to its asset in the system with its number, description, location, custodian and accounting data. Use tagging to clean up the register: assets that were never recorded and records of assets that no longer exist usually turn up. The tagging rate is measured in the pilot.
4. Baseline count
With assets tagged, the first RFID count is done. That result, with its discrepancies resolved, becomes the new reference.
5. Periodic counts by zone
From then on, the count stops being an annual event: it is done by zone as often as the company decides and, if fixed readers were installed, movements through entrances are recorded.
Common mistakes
- Buying tags without testing them on the real assets. A cheap tag that will not read on metal costs more in lost time than one designed for that surface.
- Keeping the asset system apart from accounting. Two records that are never reconciled end up diverging.
- Tagging everything without a pilot. Start with one building or one asset type, confirm the process works and then expand.
- Skipping training. The reader is simple, but the full process (tag, register, count, reconcile) needs clear owners.
The article seven RFID implementation mistakes in a warehouse goes deeper into several of these points, which apply to fixed assets as well.
Share this article: LinkedIn